A seller lead intake should first establish legitimacy and seller motivation, then move through five short fact areas: financials, occupancy, condition, price expectations, and consent. Get honest answers in those six buckets and you can decide, on the same call, whether to book a visit, nurture the lead, or walk away. Everything below gives you the exact scripts, red flags, and a simple scoring rubric to make that call with confidence.
TL;DR:
- Establish legitimacy quickly within the first 10 to 20 seconds to encourage truthful disclosures from distressed sellers.
- Prioritize motivation and timeline questions early, as they directly influence the potential for a quick sale.
- Avoid asking for exact financial figures and instead use soft language like “roughly” or “ballpark” to build trust.
- Disqualify sellers politely if they lack urgency or have unrealistic expectations, and schedule nurturing follow-ups.
- Use AI roleplay for practice to improve natural delivery, which significantly increases honest responses and deal closures.
Table of Contents
- The Six-Bucket Framework for Seller Lead Intake Questions
- What Scripts Work Best for Distressed Seller Questions?
- Red Flags and Compliance Every Caller Must Know
- How Do You Score and Move a Lead Forward?
- Why Sounding Human Beats Reading a Script
- Practice These Questions Before You Dial Live Leads
- Sources
- FAQ
The Six-Bucket Framework for Seller Lead Intake Questions
Every strong seller questionnaire, whether you run it on a cold call or a callback, works through the same six buckets in order. Skip one and you either waste a trip or scare off a seller who was never asked to trust you in the first place.
Legitimacy and rapport comes first. Distressed homeowners field calls from scammers weekly, so your opener has to do double duty: identify who you are and why you’re calling without sounding scripted. One overlooked insight worth acting on: sellers disclose more truthfully when legitimacy is established in the first 10 to 20 seconds of the call, not buried in a pitch three minutes in.
Motivation and timeline come next. Ask directly how soon they need to sell and why. A seller who says “whenever” is a different lead than one who says “before the sheriff’s sale in six weeks.”
Financials and liens require a lighter touch. You’re not offering legal advice, you’re gathering facts: mortgage balance, whether they’re behind, and any tax or judgment liens on title.
Occupancy and condition tell you what you’re actually buying. Vacant and needing work is a different offer than tenant-occupied and turnkey.
Price expectations test realism early, before you’ve invested a home visit.
Consent and contact permission close the loop, confirming how and where you can follow up.
- Verify name, relationship to the property, and decision-making authority
- Ask timeline before you ask price, motivation shapes everything downstream
- Use soft financial language: “roughly,” “ballpark,” never “exact figure required”
- Confirm occupancy status before discussing repairs
- Get explicit permission before sending documents or scheduling a visit
For decision-maker verification on probate or inherited files, NAR’s practical guide for estate cleanouts recommends confirming who actually holds authority to sign before you invest more time.
Pro Tip: If a seller hesitates on the timeline question, ask “What happens if this doesn’t sell in the next 60 days?” That single follow-up often surfaces the real urgency they didn’t volunteer.
What Scripts Work Best for Distressed Seller Questions?
Word-for-word lines beat improvisation on a cold call, especially in the first 30 seconds. Here’s a sequence you can adapt across probate, foreclosure, inherited, and vacant-property leads.
- Opener: “Hi, is this [Name]? I’m [Your Name], I buy properties in [Area], and I’m reaching out because your property at [Address] came up. Do you have two minutes?”
- Motivation: “What’s going on with the property right now, and how soon are you hoping to have this sorted?”
- Follow-up on urgency: “Is there a deadline you’re working against, like a sale date or a lender notice?”
- Follow-up on constraints: “Is anyone else involved in this decision, like family or a co-owner?”
- Financials: “Roughly how much is left on the mortgage, and are you current or behind on payments?”
- Permission for documents: “Would it be alright if I asked you to send over the most recent mortgage statement, just so I can put together a real number?”
- Occupancy: “Is anyone living there now, you, a tenant, or is it sitting empty?”
- Price test: “If everything checked out, what number would make this an easy yes for you?”
For inherited property specifically, note that heirs may face tax questions tied to stepped-up basis rules; the IRS guidance on inherited property basis is worth mentioning if the seller raises tax concerns.
- Disqualify politely: “It sounds like you’re not quite ready to sell, and that’s completely fine. Mind if I check back in a few months?”
- Soft nurture: “I’ll follow up in 30 days. In the meantime, if anything changes, here’s my direct number.”
Red Flags and Compliance Every Caller Must Know
Distressed sellers are prime scam targets, and the CFPB’s guide to foreclosure relief scams lists the exact behaviors that separate legitimate buyers from predatory ones: never ask for upfront fees, never tell a seller to stop paying their mortgage, and never guarantee a specific outcome before verifying facts.
- No upfront fees, ever, for “processing” or “guaranteeing” a sale
- Never advise a seller to stop mortgage payments or ignore servicer notices
- Refer sellers facing foreclosure to a HUD-approved housing counselor when they need real financial guidance
- Document verbal consent on every call, including date, time, and what was agreed to
The CFPB also recommends that homeowners contact their mortgage servicer early, since acting before default often preserves more options.
On the compliance side, the TCPA requires prior express consent for many autodialed calls, and the FCC’s most recent rulemaking tightened revocation rules further, meaning a seller can revoke consent in almost any reasonable way, and you’re obligated to honor it immediately. The FTC’s 2026 announcement that National Do Not Call Registry access fees are rising for FY2027, with nationwide access climbing from a much lower baseline to $23,425, signals how seriously regulators are watching phone-based lead generation. Scrub every list against the DNC registry and log opt-outs the moment they happen. For a deeper walkthrough of DNC mechanics as applied to real estate calling, see our breakdown of real estate DNC laws.
How Do You Score and Move a Lead Forward?
Once you’ve worked through the six buckets, sort the lead into one of three tiers before you hang up.
- Tier A: Motivated, clear title, timeline under 60 days. Book a visit or request the mortgage statement immediately.
- Tier B: Motivated but needs documentation, counseling, or has co-owner complications. Request lender or tax statements, refer to a HUD-approved counselor if debt is the core issue, and follow up within a week.
- Tier C: No real urgency, unrealistic price, or not the decision-maker. Log the file and schedule a 60 to 90 day nurture touch.
Capture the seller’s verbatim price number, mortgage balance if disclosed, occupancy status, and stated timeline directly in your CRM. Vague notes like “motivated seller” are useless three weeks later when you’re deciding who to call back first. Our lead qualification methods guide covers CRM field templates in more detail, and the property lead checklist gives you a fill-in-the-blank version for after-call documentation.
Pro Tip: Send a same-day confirmation text after every Tier A or B call: “Great talking today, [Name]. I’ll follow up by [date] with [next step].” It cuts no-shows on scheduled visits dramatically.

Why Sounding Human Beats Reading a Script

Sellers answer honestly when they believe you’re a real person solving a real problem, not a script reading them a checklist. That’s the whole case for talking to distressed homeowners like a person first and an investor second. The questions in this article work, but only when the delivery sounds unscripted, which means the words have to come out naturally before you’re ever on a live call with someone’s home on the line.
That’s exactly the gap scenario-based practice closes. Rehearsing a probate seller’s hesitation, or a foreclosure seller’s defensiveness, against realistic AI roleplay builds the instinct to adjust tone and follow-up questions in real time, the same instinct that separates a caller who gets a truthful answer from one who gets a hang-up.
— Dave
Practice These Questions Before You Dial Live Leads
Reading a script and running one under pressure are two different skills, and the gap between them is where deals get lost. ClosersLeague gives you AI roleplay built around the exact seller types this article covers, probate, pre-foreclosure, inherited, vacant, and more, so you can rehearse motivation and financial questions against a realistic, emotionally reactive seller before you ever risk a real lead.
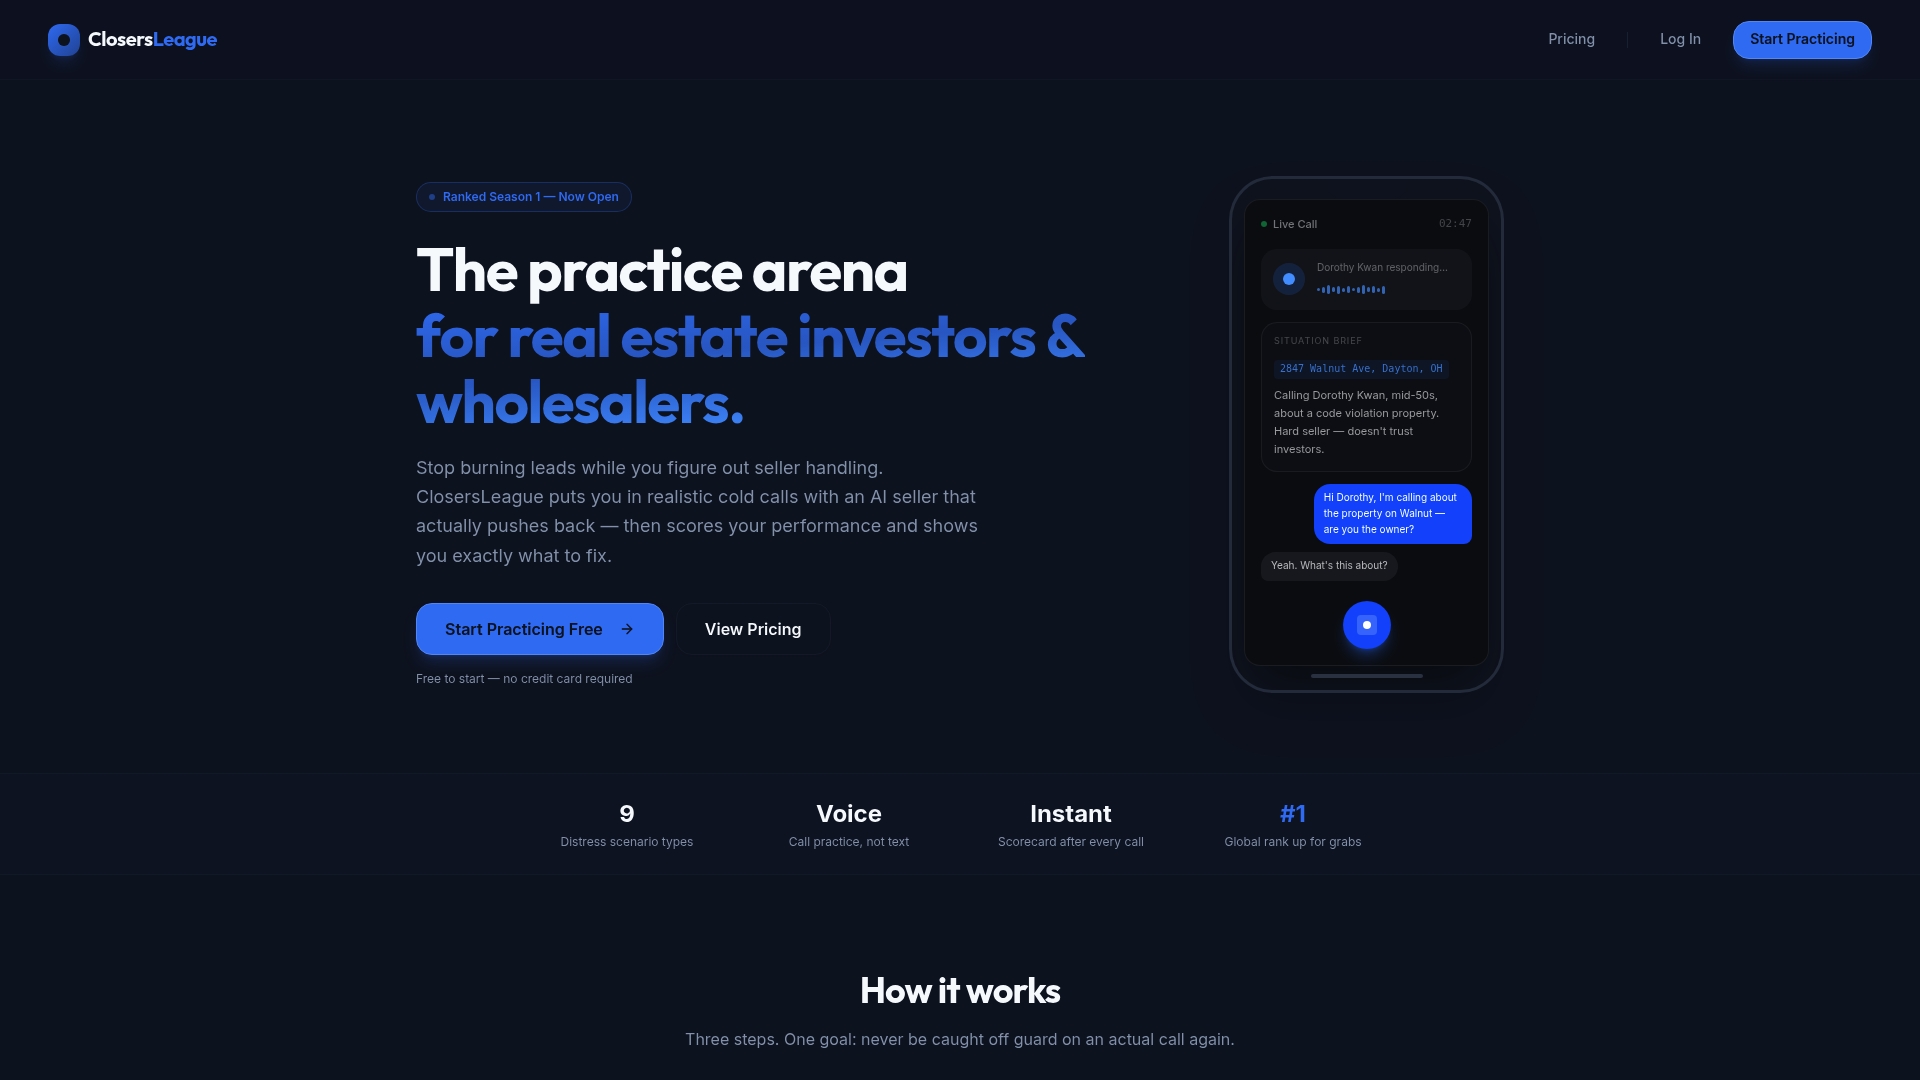
Every practice call ends with an instant scorecard breaking down rapport, objection handling, and how well you worked through the six intake buckets, plus targeted drills for whatever category scored lowest. You can start with the Starter plan and scale up as your call volume grows, or explore the real estate cold calling practice platform to see exactly which seller scenarios are available. Pick a seller type you struggle with and run three practice calls before your next real one.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
Sources
- FTC announces 2027 telemarketer fees to access National Do Not Call Registry
- How to spot and avoid foreclosure relief scams | Consumer Financial Protection Bureau
- FCC Report and Order and Further Notice of Proposed Rulemaking (TCPA updates)
FAQ
What Are the Most Important Seller Intake Questions?
The essentials cover motivation and timeline, mortgage balance and liens, occupancy status, price expectations, and consent to follow up. Skip any one of these and you risk booking a visit for a seller who was never truly ready to sell.
How Do I Disqualify a Seller Without Burning the Lead?
Acknowledge their situation, note that timing isn’t right, and ask permission to check back in a few months. This keeps the relationship warm for nurture campaigns instead of closing the door outright.
What Should I Avoid Asking or Saying on a Foreclosure Call?
Never suggest a seller stop paying their mortgage or promise a guaranteed outcome before verifying facts, both are classic scam red flags according to the CFPB. Refer sellers who need financial guidance to a HUD-approved housing counselor instead.
Do I Need Consent Before Calling a Seller Lead?
Yes, TCPA rules generally require prior express consent for autodialed or prerecorded calls, and you must honor revocation requests immediately per FCC rules. Document consent and opt-outs on every call to stay protected.
Can ClosersLeague Help Me Practice These Intake Calls?
Yes, ClosersLeague offers AI roleplay scenarios for probate, foreclosure, inherited, and other distressed seller types, with instant scorecards after each call. Plans start at $5 per month with the Starter tier, scaling up through Growth and Pro as your practice needs grow.