A good subject-to call script does four things in order. It opens with permission, learns the seller’s situation before mentioning any offer, explains plainly that the existing mortgage stays in the seller’s name, and ends with one agreed next step. Below is the full script, the questions to ask, honest answers to the objections you will hear, and how to practice it until it sounds natural.
TL;DR
- In a subject-to deal, you take title and make the payments, but the loan stays in the seller’s name. Say that out loud, in plain words, on the call.
- Learn motivation, timing, property and money, in that order, before you talk terms.
- The lender can enforce a due-on-sale clause under federal law. Never hide a transfer from the lender, and tell sellers to get their own attorney.
- End every call with one next step, not a pressure close.
- Rehearse the hard moments (liability, credit, “what if you stop paying?”) before you dial real homeowners.
Table of Contents
- What “subject to” means in one breath
- Who this script is for
- The subject-to call script, step by step
- Objections you’ll hear, and accurate answers
- Presenting the offer and the paperwork
- Perspective: why we tell investors to rehearse this call
- Practice the script before you dial
- Practice with ClosersLeague
- FAQ
- Sources
What “subject to” means in one breath
You can’t script a deal you can’t explain. In a subject-to purchase, the buyer takes title to the property and agrees to make payments on the seller’s existing mortgage. The loan is not refinanced or formally assumed, and it remains in the seller’s name, so the seller stays liable to the lender even though someone else owns the home.
That is different from an assumption. An assumption needs lender approval and puts the obligation on the buyer. Subject-to leaves the original borrower on the hook. Business Insider’s explainer notes that the buyer receives the deed and can control, rent or refinance the property, while the seller’s loan keeps the same terms.
Your whole script rests on this: ownership moves, the loan doesn’t. Every line below is built to say it honestly.

Who this script is for
Subject-to conversations fit sellers who have a loan worth keeping, often at a low rate, and a reason they can’t keep carrying the property. Typical situations are pre-foreclosure, divorce, an inherited home with a mortgage still attached, a tired landlord, or an out-of-state owner. If you work those lists, our guide to cold calling foreclosure properties covers the first-contact side in more depth.
A subject-to pitch is not a cold opener. It is the second or third stage of a conversation you earn by listening. Don’t lead with it.
The subject-to call script, step by step
Adapt the wording to your voice. Keep the order.
Step 1: Open with permission
Identify yourself and your company, say why you’re calling, confirm you have the right person, and ask whether it’s a good time. If it isn’t, schedule a better one.
“Hi, is this Maria? This is Jake with Ridgeline Home Buyers. I’m calling about the house on Elm Street. Did I catch you at an okay time, or should I call back later today?”
If Maria says no, offer two times and end the call warmly. A scheduled callback beats a rushed conversation every time.
Step 2: State your reason, then ask about her situation
“I buy houses in the area, and I’m reaching out to owners who might be open to a conversation about selling. Is that something you’ve thought about at all?”
Then stop talking. Follow with open questions:
- “What’s going on with the property right now?”
- “What made you start thinking about selling?”
- “What happens if it doesn’t sell?”
- “Have you thought about listing it with an agent?”
These are the discovery questions that surface real motivation. Learn the seller’s situation in this order: motivation, timing, property, money. Do not start with an offer.
Step 3: Confirm authority
“Is the house in your name only, or is anyone else on the title?”
In probate and divorce, this question matters more than any other. If a spouse, sibling or co-heir must sign, they need to be part of the decision.
Step 4: Ask the loan questions
Only once she’s talking openly about her situation, move to the mortgage. Before discussing a subject-to offer, you need to know who holds the mortgage, how many payments are behind, the most recent payment amount, the remaining balance, and whether there are arrears or liens, including tax or mechanics liens.
“So I can see whether I can help, can I ask a few quick questions about the mortgage? Who’s the lender? Roughly what’s the balance? What’s the monthly payment, and are you current or behind?”
Also ask about the interest rate and whether the payment includes taxes and insurance (PITI). Know that nearly all conventional loans written in recent decades include a due-on-sale clause, which matters in Step 6.
Capture the answers in a simple grid:
| Item | What to record |
|---|---|
| Lender / servicer | Name, loan type if known |
| Balance | Approximate payoff |
| Rate and payment | Monthly PITI amount |
| Status | Current, or number of payments behind |
| Liens | Taxes, mechanics liens, judgments |
| Title | Everyone who must sign |
| Condition | Repairs, occupancy |
If you want a fuller qualification routine, see how to qualify real estate leads and keep a property lead checklist open while you dial.
Step 5: Explain the transaction plainly
This is the line that decides whether the seller trusts you. Say it simply and completely:
“Here’s how it would work. You’d transfer ownership to me. Your current mortgage stays in your name, exactly as it is. I’d take over making the mortgage payments, plus the taxes and insurance. This is not the bank approving a new loan for me, so you’d still be listed on that mortgage until it’s paid off or refinanced. That’s why I’d want you to have your own attorney review everything before you sign.”
The core points to land: ownership transfers, the loan stays in the seller’s name, the buyer pays the mortgage, taxes, insurance and other agreed items, and the seller remains responsible to the lender if the buyer fails to pay.
If the seller asks how you’d pay later or what your long-term plan is, be ready to talk about your exit. Investors who plan to refinance out or hold the property often review DSCR loan options for investors before they make promises on a call, so the answer they give is one they can keep.
Step 6: Handle the due-on-sale question honestly
A well-informed seller, or the seller’s attorney, will ask about the due-on-sale clause. Don’t dodge it.
“Good question. Most mortgages have a clause that lets the lender demand the full balance if the property transfers without their consent. It’s their right, not their obligation, and in practice lenders often don’t act while payments stay current, but I can’t promise that. That’s exactly why I want your attorney involved.”
The law backs this up. Under 12 U.S.C. §1701j-3, lenders may generally enforce due-on-sale clauses, with listed exceptions for things like transfers at death, transfers to a spouse or children, and certain divorce transfers. Those exceptions apply to specific situations and don’t turn a sale to an investor into a protected transfer.
One more point belongs in your own playbook, not just the script. The North Carolina Real Estate Commission warns that concealing a subject-to transfer from the lender is generally loan fraud and advises brokers, buyers and sellers to get qualified real-property legal advice. Never coach a seller to mislead their lender. Rules also vary by state, so have a local real estate attorney review your documents.

Step 7: Agree on one next step
Don’t push for a decision on the first call. Pick one:
- A walkthrough of the property
- A callback on a specific date
- Sending an overview for the seller and their attorney to review
- A respectful close if it isn’t a fit
“Based on what you’ve told me, I’d like to walk the property and run the numbers. Would Thursday at 4 or Friday morning work better?”
If you’d like to text a confirmation, ask permission first and include an opt-out such as replying STOP. Verify the federal and state telemarketing and messaging rules that apply to you. Our guide to vacant property cold calling walks through the TCPA basics.
Objections you’ll hear, and accurate answers
Subject-to objections are rarely about price. They are about risk. Answer each one truthfully.
“Am I still responsible for the loan?”
Yes. Say so. The loan stays in the seller’s name, so a missed payment lands on the seller’s credit. Georgia Title & Escrow warns that a subject-to transfer can expose a seller to acceleration, credit damage and foreclosure if the buyer fails to pay, and recommends sellers retain their own counsel.
“You are, until the loan is paid off or refinanced. That’s the tradeoff. Here’s how I’d protect you: payments made through a third-party servicer so you can see the record, and your attorney reviewing the agreement.”
“What if you stop paying?”
Don’t get defensive. The Orlando Law Group describes seller risks including continued liability, credit damage, foreclosure and trouble qualifying for another mortgage. Acknowledge that.
“That’s the right thing to worry about. If payments stopped, it would hurt your credit, and I won’t pretend otherwise. That’s why I’d document every payment and want a written agreement your attorney has signed off on.”
Documenting payments and involving a real estate attorney are the steps Rocket Mortgage recommends for managing these risks.
“Will the bank find out?”
Don’t promise secrecy. Don’t promise the bank won’t act.
“I can’t promise how the lender would respond. The clause gives them the right to ask for the full balance. I’d rather you know that now and talk it through with your attorney than be surprised later.”
“I just want out. Why not list it?”
This is a fair question, and the discovery work in Step 2 gives you the answer. If the seller is behind, needs speed, or has little equity, explain how your offer addresses the stated goal. If it doesn’t fit, say so and close respectfully. A graceful no builds referrals.
“Stop calling me.”
Give no rebuttal. Say thank you, record the request, and mark the number Do Not Contact before your next dial.
Presenting the offer and the paperwork
When you reach the offer stage, be transparent. Explain your role and process, identify costs and repairs, and make sure required disclosures and paperwork are in order. Ethical wholesaling guidance from Follow Up Boss says the same.
Repairs belong in that conversation. A seller who learns about a failing sewer line after closing feels misled. A pre-offer walk-through that includes a plumbing inspection checklist helps you price the property accurately and set honest expectations.
Typical terms are worth knowing too. One investor guide describes many sellers receiving little beyond debt relief, or roughly $1,000 to $5,000 in cash, with closing by warranty deed and payments run through a third-party loan servicer for clear records. Treat those as ranges, not promises, and let your attorney set the terms for your state.
Perspective: why we tell investors to rehearse this call
Subject-to is the call where a rushed or vague answer costs you the deal and, worse, the seller’s trust. Sellers in foreclosure, probate or divorce are stressed. They hear every pause. If you stumble on “am I still liable?” they stop believing the rest.
That’s why we built ClosersLeague around practice, not theory. Our AI roleplay lets you run these calls against realistic distressed sellers, with different emotional states and objections, then see an instant scorecard and detailed feedback. Targeted drills let you repeat the exact moment that tripped you up until it’s clean.
Role-playing with a colleague is better than nothing, but a colleague rarely plays an angry, grieving or suspicious seller the same way twice. We think the reps, scored honestly, are what turn a script into a skill. Stop winging it. Start drilling.
Dave
Practice the script before you dial
Reading a script once doesn’t prepare you for a seller who interrupts at line two. Here is a simple routine:
- Drill the explanation. Say the Step 5 paragraph aloud until it takes under 30 seconds and doesn’t sound read.
- Rehearse the three hard questions: liability, “what if you stop paying,” and due-on-sale.
- Practice different sellers. A probate heir and a pre-foreclosure owner need different pacing. Our inherited property practice scenario is a good place to start for estate situations.
- Review each call. Score your opener, discovery, objection handling and close. Fix one weakness per session.
- Log the call within ten minutes: facts, unknowns, next step and its date.
If you want to see how a script fits a wider system, read our guide on an investor script workflow and what an investor script actually is. For a different structure, compare it with our seller financing call script.
Practice with ClosersLeague
ClosersLeague is an AI cold calling training platform for real estate investors and wholesalers. You get scenario-based voice practice across distressed seller types, real-time coaching, performance scorecards, targeted skill drills and leaderboards. Plans are priced by the number of AI practice calls: Starter is $5 per month, Growth is $10 per month and Pro is $18 per month, and the free trial includes a limited number of calls.
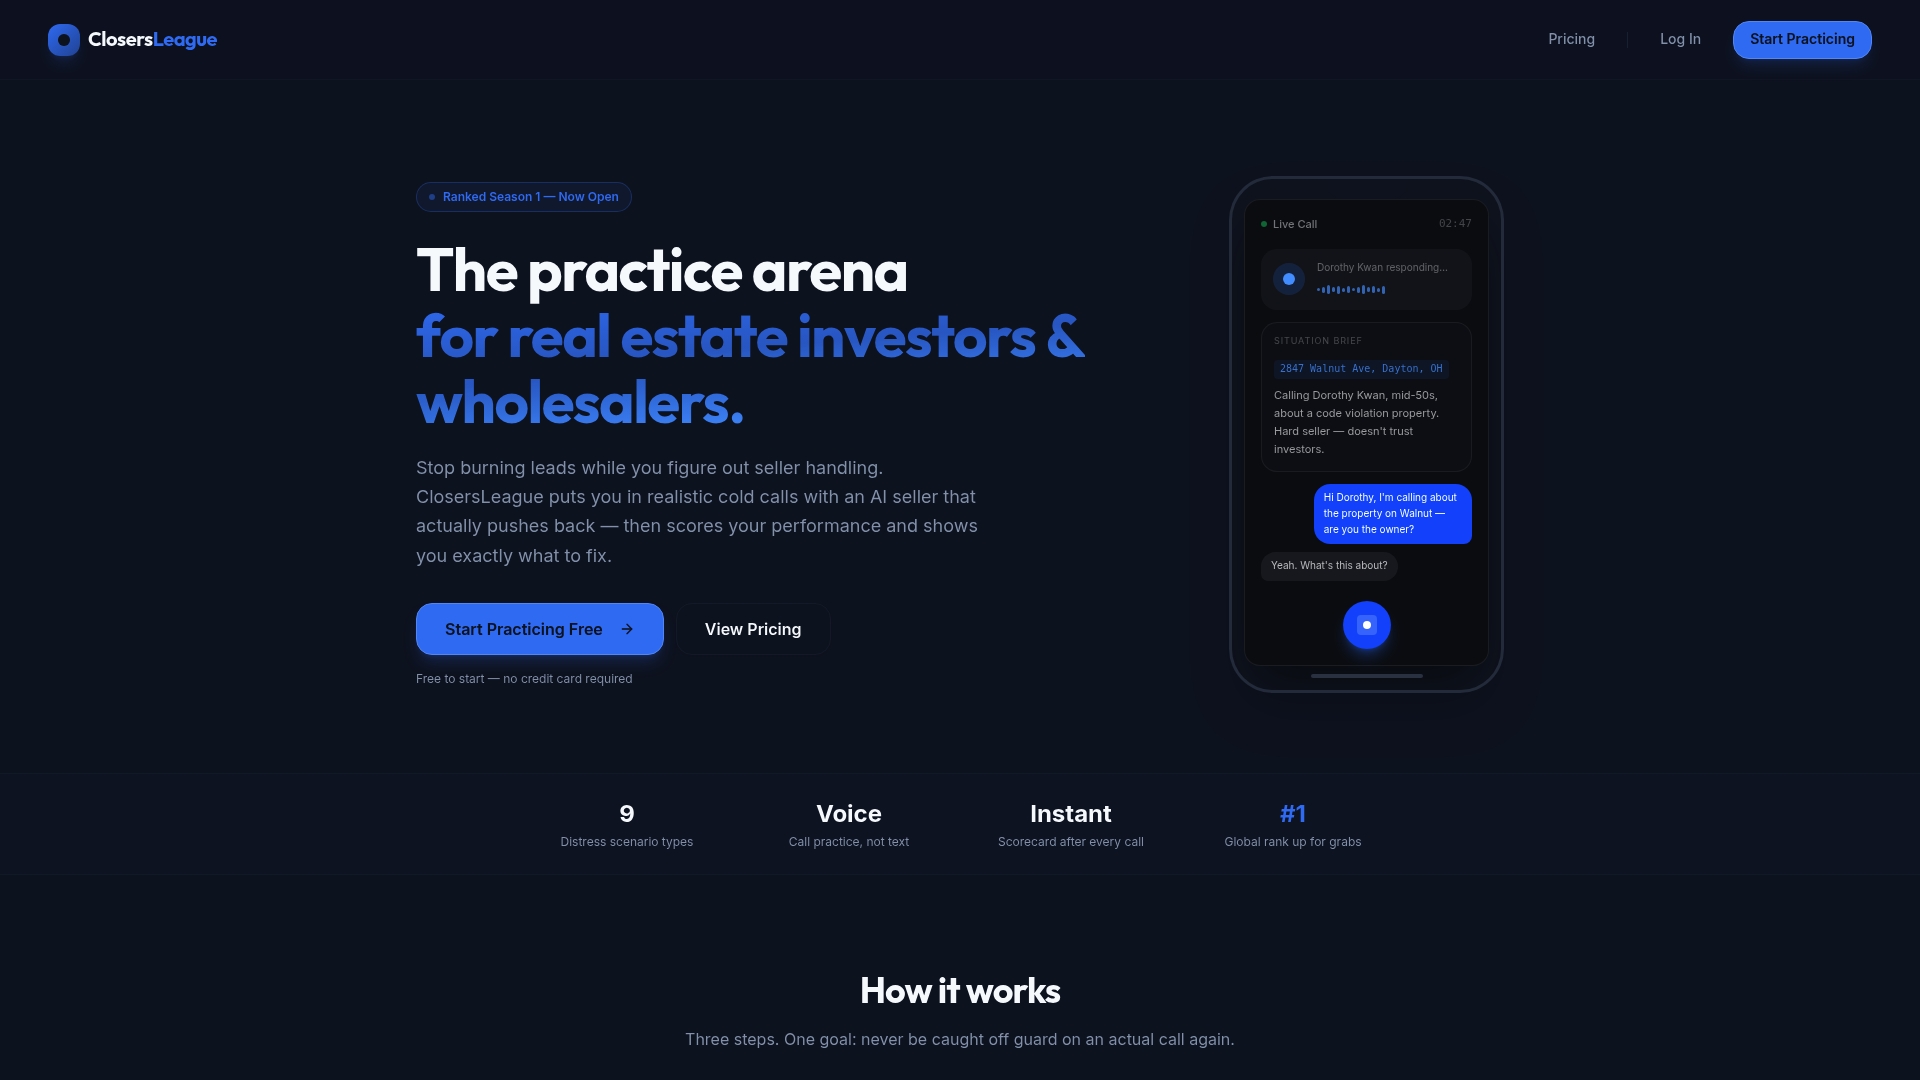
Pick a scenario, run the script above, and read your scorecard. See the plans and start practicing.
FAQ
What is a subject-to call script?
It is a structured conversation outline for talking with a homeowner about buying their property while the existing mortgage stays in place. It covers the opener, discovery, loan questions, a plain explanation of the deal, objection answers and a next step.
Do I mention subject-to on the first cold call?
Usually no. Open with permission, learn the seller’s motivation, timing, property and money first, and bring up the structure only when the situation fits. Leading with a complex structure before you have rapport tends to make sellers defensive.
Is a subject-to purchase legal?
It is a recognized creative financing structure, but the lender can generally enforce a due-on-sale clause under federal law. Hiding a transfer from the lender is generally loan fraud. Talk to a real estate attorney in your state before you close.
What should I ask a seller about their mortgage?
Ask who the lender is, the balance, the interest rate, the monthly payment, whether they are current or behind, and whether there are tax or mechanics liens. Also confirm everyone on title.
How should I end a subject-to call?
Agree on one next step, such as a walkthrough, a callback date or sending documents for the seller’s attorney to review. Don’t pressure the seller to decide on the spot, and record the outcome right after the call.
Sources
- What is ‘subject to’ in real estate? (Rocket Mortgage)
- What Is Subject-to Financing (Business Insider)
- The Steps to a Subject To Real Estate Deal (REIkit)
- Finding and Qualifying Subject-To Candidates (HiddenDealPro)
- Preemption of Due-on-Sale Prohibitions, 12 U.S.C. §1701j-3
- NCREC Bulletins: Acquiring title subject to a seller’s mortgage
- Wholesaling, Double Closings, Assignments (Georgia Title & Escrow)
- Subject-To Transactions: Risks Sellers Need to Know (The Orlando Law Group)
- Wholesale real estate guide (Follow Up Boss)
- Subject To Real Estate: Complete Investor Guide (Deal Run)